
Longevity Risk Is Rising. The Capital Response Requires More Than One Tool.
Executive Summary
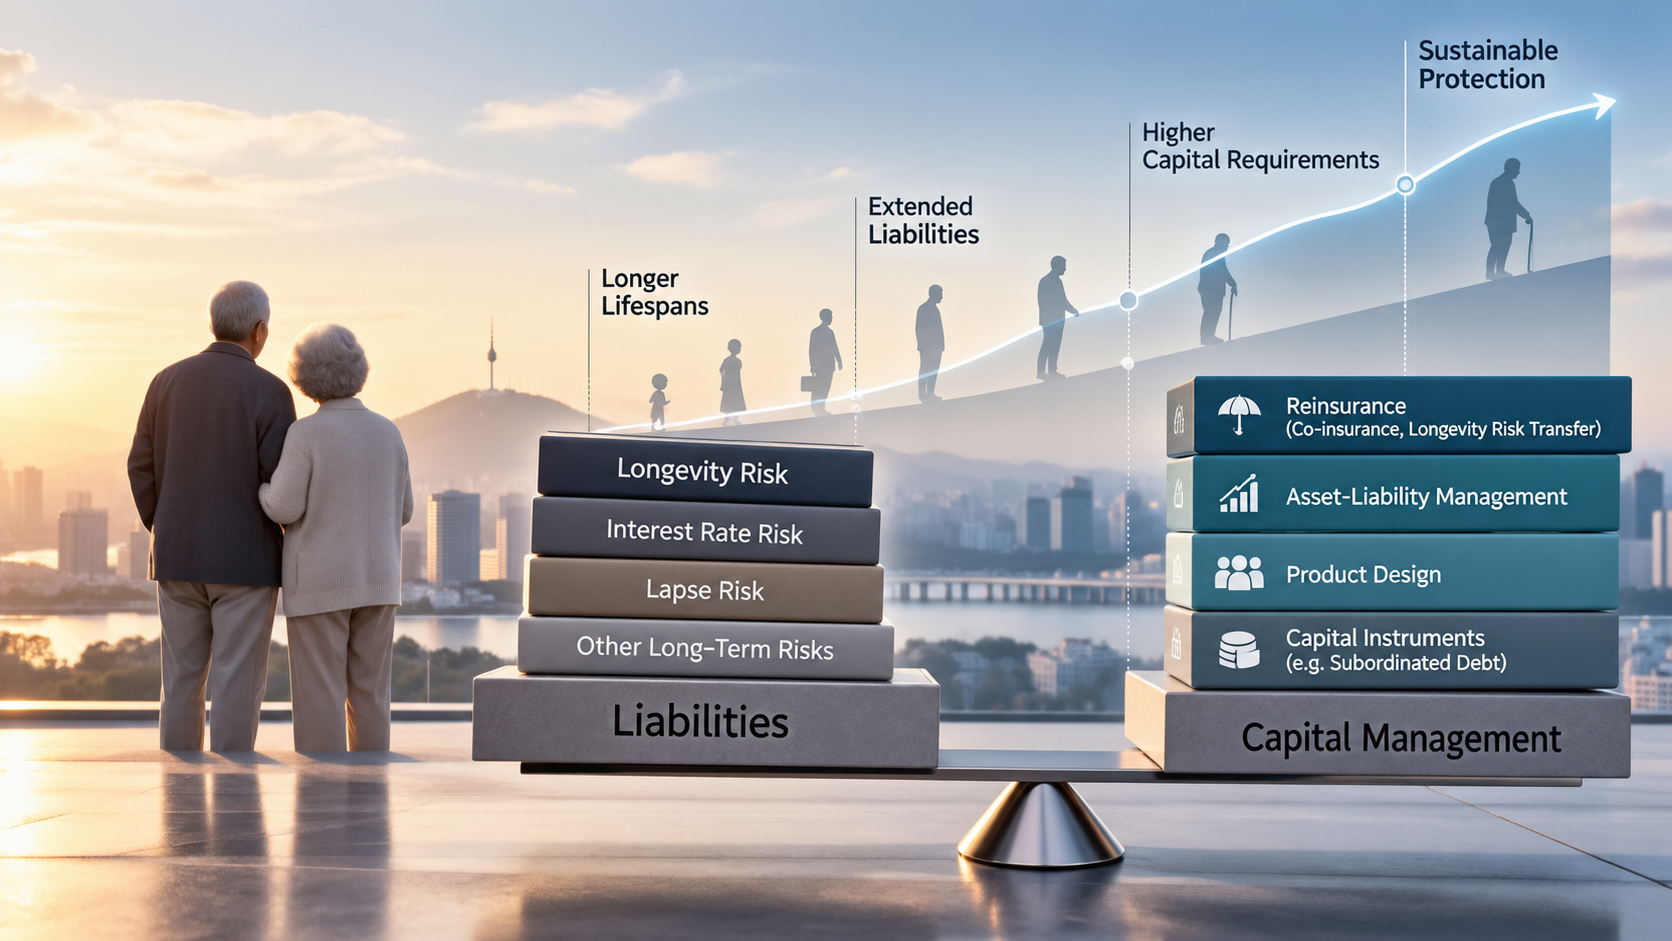
As demographic structures shift toward older populations, life insurers face a growing challenge in managing long-duration liabilities and longevity exposure. Longer lifespans can extend benefit payment periods and increase the sensitivity of balance sheets to longevity, interest-rate and other long-term risks under modern solvency frameworks such as K-ICS and Solvency II.
Capital management therefore requires more than simply raising additional capital. Asset-liability management, product design, reinsurance and other risk-transfer solutions can each play different roles depending on the underlying source of capital pressure.
This article examines how structural reinsurance solutions—including co-insurance and longevity risk transfer—can complement broader balance-sheet management. The objective is not to identify a single solution, but to match the capital response to the risks that are actually driving the requirement.
🇰🇷 한국어 | Full Translation
1. Key Dynamics: 장수 리스크와 자본의 압박
과거 생명보험의 위험관리에서는 사망위험이 중요한 축을 차지해 왔습니다. 그러나 인구 고령화와 기대수명 연장으로 인해, 특히 연금과 평생급부 포트폴리오에서는 **장수위험(Longevity Risk)**의 중요성이 커지고 있습니다.
가입자가 예상보다 오래 생존하면 연금이나 장기급부의 지급기간이 늘어날 수 있으며, 이는 해당 부채의 가치와 자본요구에 영향을 줄 수 있습니다. 현대적인 경제가치 기반 지급여력제도에서는 이러한 장기위험과 자산·부채의 듀레이션 관리가 더욱 중요해지고 있습니다.
2. Structural Comparison Table
| 구분 | 전통적 단순 재보험 | 공동재보험 (Co-insurance) |
|---|---|---|
| 위험 이전 범위 | 주로 사망·질병 등 보험위험 | 구조에 따라 보험위험과 함께 금리·해약 등 보다 넓은 위험 이전 가능 |
| 자본 경감 효과 | 주로 보험위험 요구자본을 중심으로 제한적 | 실제 위험이전 및 규제상 인정범위에 따라 보다 큰 자본효과 가능 |
3. Actionable Insights
- ALM의 한계 보완: 자산운용과 듀레이션 관리만으로 장기부채의 위험을 충분히 관리하기 어려운 경우, 재보험을 통한 부채위험 이전을 함께 검토할 수 있습니다.
- 자본비용의 비교: 자본확충이나 후순위채 발행과 비교해, 재보험을 통한 위험이전이 장기적으로 더 효율적인 대안이 될 수 있습니다. 다만 실제 경제성은 거래비용, 위험이전 효과와 자본인정에 따라 달라집니다.
✈️ Co-Pilot’s Dispatch
한때 생명보험사들이 가장 두려워하던 것은 고객의 ‘조기 사망’이었습니다. 이제는 반대로, 고객이 120세까지 건강하게 살면서 매달 연금을 꼬박꼬박 받아가는 상황도 중요한 고민거리가 됐습니다.
의학의 발전은 인류에게 분명한 축복입니다. 다만 보험사 CFO 입장에서는 축하할 일이 하나 늘어날 때마다 liability duration도 조용히 한 칸씩 길어지는 셈입니다. 😄
✈️ Captain’s Salute
초고령화에 대한 대응은 단순히 위험을 피하는 문제가 아니라, 장기 부채와 자본을 어떻게 함께 관리할 것인가의 문제입니다. ALM, 자본수단과 재보험을 적절히 조합해 재무상태표의 유연성을 높이는 것이 장기적인 안정성과 성장의 핵심이 될 수 있습니다.
1. Key Dynamics: Longevity Risk & Regulatory Pressure
Mortality risk has traditionally been a central concern for life insurers. As populations age and life expectancy increases, however, longevity risk is becoming increasingly important—particularly for annuity and lifetime-benefit portfolios.
When policyholders live longer than expected, annuity and long-term benefit payments may continue for longer periods, affecting liability values and capital requirements. Under modern economic-value-based solvency frameworks, managing these long-duration risks and the asset-liability duration profile becomes increasingly important.
2. Structural Comparison Table
| Category | Traditional Reinsurance | Co-Insurance / Capital Structuring |
|---|---|---|
| Risk Transfer | Primarily mortality, morbidity and other insurance risks | Depending on structure, broader transfer including insurance, interest-rate and lapse risks |
| Capital Relief | Typically focused on insurance-risk capital | Potentially broader capital impact, subject to actual risk transfer and regulatory recognition |
3. Actionable Insights
- Beyond Asset Management: Where ALM and duration management alone cannot sufficiently address long-term liability risk, reinsurance-based liability risk transfer may also be considered.
- Optimising Cost of Capital: Reinsurance may, in some circumstances, provide a more efficient long-term alternative to additional capital or repeated subordinated-debt issuance. The actual economics depend on transaction cost, risk-transfer effectiveness and regulatory capital recognition.
✈️ Co-Pilot’s Dispatch
Once upon a time, life insurers feared premature mortality above all else. Today, another nightmare has joined the list: policyholders living happily to 120 and collecting their annuity cheques every month.
Medical progress is unquestionably good news for society. For a life insurer’s CFO, however, every extra year of healthy life can quietly add another year to the liability tail. 😄
✈️ Captain’s Salute
Managing hyper-aging is not simply about avoiding risk. It is about managing long-duration liabilities and capital together.
A flexible combination of ALM, capital instruments and reinsurance can help insurers strengthen balance-sheet resilience and preserve capacity for long-term growth.
🇯🇵 日本語 | Full Translation
1. Key Dynamics:長寿リスクと資本規制の圧力
生命保険会社にとって、死亡リスクは従来から重要なリスクの一つでした。しかし、人口の高齢化と平均寿命の延伸に伴い、特に年金や終身給付ポートフォリオでは、**長寿リスク(Longevity Risk)**の重要性が高まっています。
契約者が想定より長く生存すると、年金や長期給付の支払期間が延び、負債価値や必要資本に影響を与える可能性があります。経済価値ベースのソルベンシー規制の下では、こうした長期リスクと資産・負債のデュレーション管理がより重要になります。
2. Structural Comparison Table
| 区分 | 伝統的再保険 | 共同再保険 / Capital Structuring |
|---|---|---|
| リスク移転 | 主として死亡・疾病などの保険リスク | 取引構造により、保険リスクに加えて金利・解約リスクなどをより広く移転可能 |
| 資本削減効果 | 主として保険リスクに係る所要資本が中心 | 実際のリスク移転と規制上の認定に応じ、より広い資本効果が得られる可能性 |
3. Actionable Insights
- ALMの限界を補完する: ALMやデュレーション管理だけでは長期負債リスクを十分に管理できない場合、再保険による負債リスクの移転を併せて検討することができます。
- 資本コストを比較する: 追加資本や劣後債の継続的な発行と比較して、再保険によるリスク移転が長期的により効率的となる場合があります。ただし、実際の経済性は取引コスト、リスク移転効果、規制上の資本認定によって異なります。
✈️ Co-Pilot’s Dispatch
かつて生命保険会社が最も恐れていたのは、契約者の早期死亡でした。今では別の悪夢も加わっています。契約者が120歳まで元気に暮らし、毎月きちんと年金を受け取り続けることです。
医療の進歩は社会にとって間違いなく朗報です。ただし生命保険会社のCFOにとっては、健康寿命が1年延びるたびに、負債のテールも静かに1年延びていくことがあります。😄
✈️ Captain’s Salute
超高齢化への対応は、単にリスクを避けることではありません。長期負債と資本を一体として管理することです。
ALM、資本手段、再保険を柔軟に組み合わせることで、保険会社はバランスシートの耐久力を高め、長期的な成長余力を維持することができます。
🇹🇼 繁體中文 | Summary
全球人口持續高齡化,使壽險公司面臨日益明顯的長期負債與長壽風險管理壓力。對於年金及終身給付類業務而言,壽命延長可能拉長給付期間,進而影響負債價值與資本需求。
因此,資本管理不能只依賴單一工具。ALM、資本工具、商品設計及再保險各自扮演不同角色。共同再保險及其他風險移轉安排,在符合實際風險移轉與監理資本認定要求的情況下,可以成為優化資產負債表的重要補充。
真正需要回答的問題並不是「哪一種工具最好」,而是:究竟是哪一項風險正在驅動資本需求,以及哪一種資本管理方式最適合處理該風險。
✈️ Captain’s Salute
因應超高齡化,不只是規避風險,而是需要同時管理長期負債與資本。透過靈活結合ALM、資本工具與再保險,壽險公司可以提升資產負債表的韌性,並為長期成長保留更大的策略空間。
Technical Note: Longevity risk does not affect all life insurance portfolios in the same way. Its capital impact depends on product mix, guarantee structure, liability duration, natural hedging and the applicable solvency framework. Co-insurance and other risk-transfer structures may reduce specific balance-sheet risks only where the contractual transfer and regulatory capital recognition requirements are satisfied.
Sources
- Korea Financial Services Commission, K-ICS Final Framework and Transitional Measures
- Korea Financial Services Commission, Introduction of Coinsurance (2020)
- EIOPA, Solvency II Longevity Risk Sub-module