
The future belongs not to the company with one more policy, but to the network that can turn everyday risks into seamless protection.
Executive Summary
Affinity insurance begins with an existing relationship: a manufacturer and its vehicle owner, a retailer and its customer, a platform and its user, or a pet-care provider and a pet owner. Embedded insurance goes one step further by placing protection inside the purchase or service journey. Embedded protection broadens the idea again, combining insurance, warranties and service solutions around the customer’s actual problem.
Korea does not lack possible use cases. Extended warranties, product protection, travel, mobility, pet care and other everyday services all contain protection gaps. Yet the market remains relatively underdeveloped because converting a promising idea into a compliant, serviceable and reinsurable programme requires coordination across distribution, technology, administration, claims, underwriting and risk capital.
The next phase will therefore not be defined by attaching one more policy at checkout. It will be defined by the organisation—or network—that can build a reusable operating layer connecting the affinity partner, customer, insurer, digital distributor and reinsurer.
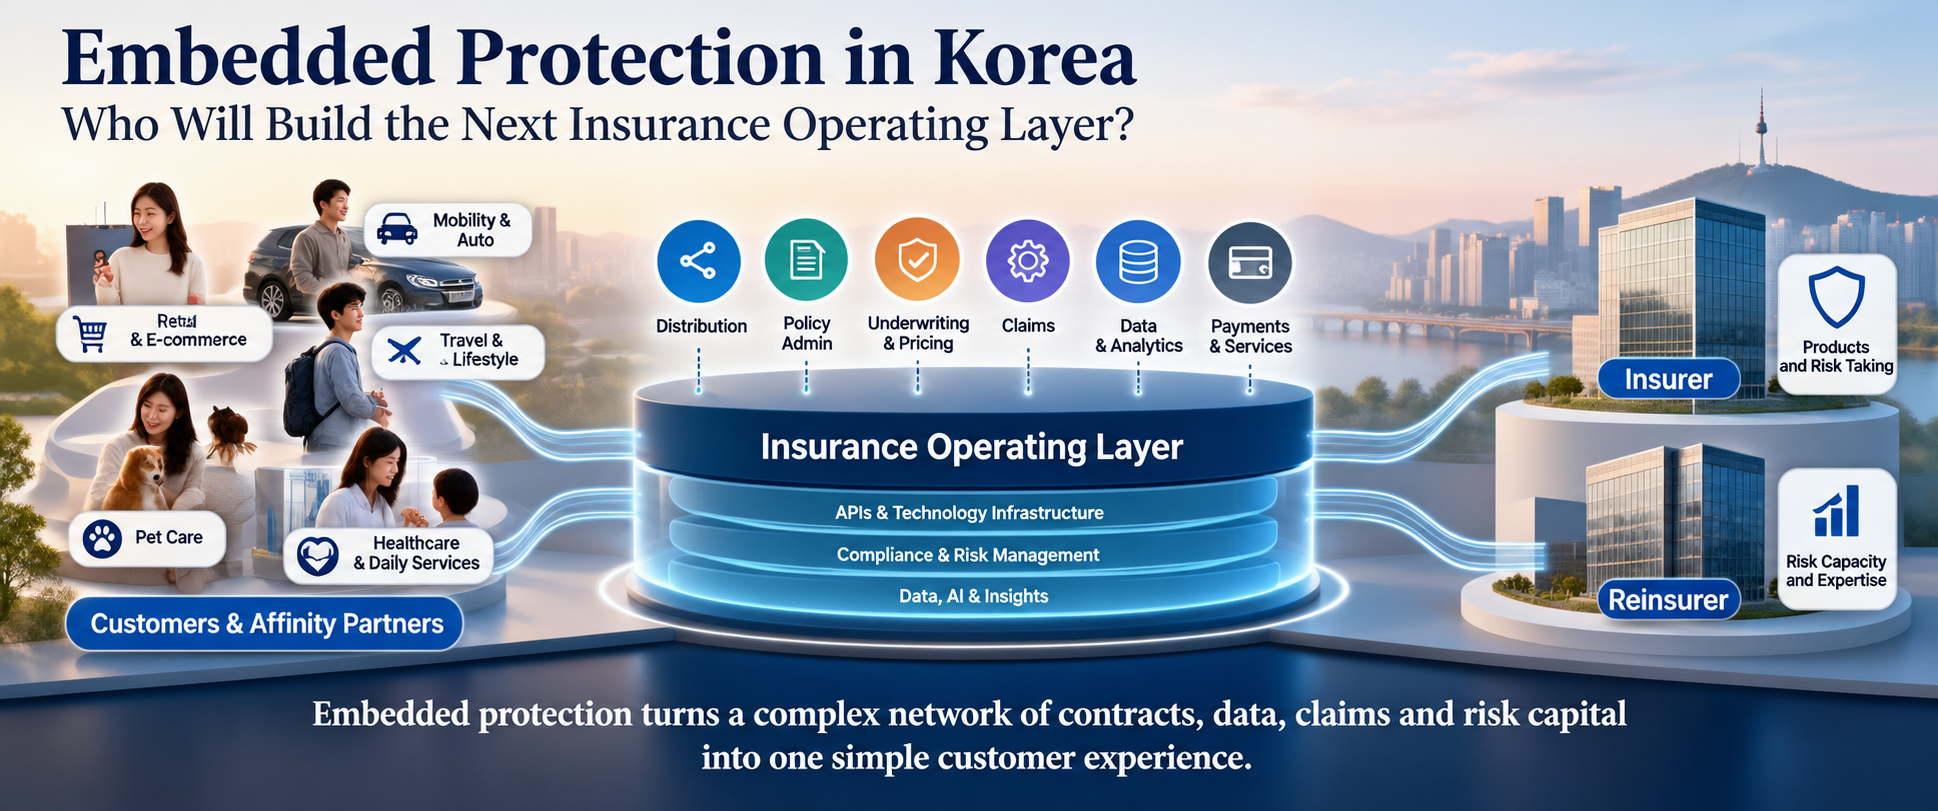
Embedded protection turns a complex network of contracts, data, claims and risk capital into one simple customer experience.
🇰🇷 한국어 | Full Translation
1. Affinity에서 Embedded Protection으로
Affinity Insurance는 이미 형성된 고객관계에서 출발합니다. 자동차 제조사와 차량 소유자, 판매점과 고객, 플랫폼과 이용자, 반려동물 서비스업체와 보호자처럼 연결될 수 있습니다. 공통점은 특정 보험종목이 아니라, 관련된 protection need를 가진 명확한 고객집단에 접근할 수 있다는 것입니다.
Embedded Insurance는 이러한 보장을 다른 상품의 구매 또는 서비스 이용 과정 안에 배치합니다. 고객이 보험회사를 먼저 찾아가는 것이 아니라, 다른 상품을 구매하거나 예약하고, 구독하거나 서비스를 이용하는 적절한 시점에 보장이 제공됩니다.
Embedded Protection은 이 개념을 한 단계 더 확장합니다. 고객이 원하는 것은 보험증권 자체가 아닙니다. 차량을 수리하고, 파손된 제품을 교체하고, 취소된 여행 문제를 해결하거나, 반려동물 치료비 부담을 처리하는 것입니다. 보험은 Warranty, Assistance, 수리 네트워크 및 기타 서비스와 함께 이러한 문제를 해결하는 하나의 구성요소가 될 수 있습니다.
2. 보험은 점점 덜 보이게 된다
보험이 사라질 가능성은 낮습니다. 오히려 고객이 이미 이용하고 있는 상품과 서비스 안으로 들어가면서 점점 덜 보이게 될 가능성이 높습니다.
자동차를 구매하면 향후 고장위험이 생깁니다. 새 타이어를 장착하면 우발적인 파손위험이 생기고, 반려동물을 키우면 치료비 위험이 발생합니다. 이러한 위험은 기존의 소매거래가 끝나는 지점에서 시작되며, 각각 새로운 고객서비스 관계를 만들 수 있습니다.
목표는 모든 결제 단계에 보험을 억지로 끼워 넣는 것이 아닙니다. 제휴사의 고객여정에서 실제 protection gap을 찾아내고, 필요한 순간에 자연스럽게 작동하는 보장을 설계하는 것입니다.
3. 시장이 아직 충분히 성장하지 못한 이유
한국에 Affinity 아이디어가 부족한 것은 아닙니다. 보험연구원은 자동차 품질보증 연장보험, 전자제품 보증기간 연장보험, 반송보험과 자동차 관련 보장 등을 국내 Embedded Insurance 사례로 소개하면서, 플랫폼과 인슈어테크 역량을 향후 시장 성장의 중요한 동력으로 지적한 바 있습니다.
어려운 점은 유망한 아이디어를 지속 가능한 programme으로 전환하는 과정입니다. 제휴사는 고객이 쉽게 이해할 수 있는 단순한 혜택을 원합니다. 반면 보험회사는 데이터, 가격, 담보범위, 판매방식과 소비자보호 요건을 검토해야 합니다. 모바일 가입화면은 시작에 불과합니다. 이후 계약변경, 해지, 환불, 보험금 청구, 심사, 수리 또는 교체, 지급과 제휴사 정산까지 모두 제대로 작동해야 합니다.
신규 Affinity 위험은 신뢰할 만한 경험통계가 부족할 수 있습니다. 초기 판매량이 적으면 여러 참여자가 부담해야 하는 운영비용을 정당화하기 어렵습니다. 반대로 빠르게 성장하면 가격과 운영절차가 충분히 성숙하기 전에 누적위험, 손해율 변동성과 고객지원 부담이 커질 수 있습니다. 고객에게 인기 있는 상품과 운영상 지속 가능한 보험 programme은 같은 것이 아닙니다.
시장이 성장하지 못하는 이유는 아이디어가 부족해서가 아니다. 아이디어를 규제에 부합하고, 실제 운영이 가능하며, 재보험이 가능한 programme으로 전환하기 어렵기 때문이다.
4. 플랫폼은 어디에서 시작되는가
자동차 Extended Warranty, 타이어 파손보장과 Pet Insurance는 서로 관련 없는 상품처럼 보입니다. 그러나 운영 측면에서는 고객확인, 모바일 가입, 계약관리, 청구접수, 서류와 이미지 제출, 심사, 지급 및 정산 등 많은 요소를 공유합니다.
바로 이것이 재사용 가능한 운영기반이 필요한 이유입니다. 상품마다 새로운 시스템을 구축하는 대신, 하나의 공통 operating layer 위에서 보장대상, 가격, 면책사항과 보험금 청구 규칙을 변경해 여러 Affinity programme을 지원할 수 있습니다.
이러한 플랫폼이 처음부터 완성된 형태로 등장하는 경우는 드뭅니다. 보험회사의 영업조직이 고객에게 더 가까이 다가가 특정한 필요에 맞는 서비스를 만들고, 이후 이를 별도 사업으로 발전시킬 수 있습니다. 보험대리점이 가입과 계약관리에서 출발해 청구, 정산과 데이터 기능까지 흡수할 수도 있습니다. 온라인 또는 오프라인 판매자가 기존의 고객·거래처 관리에서 출발해 protection 영역 자체로 확장할 수도 있습니다.
공통적인 패턴은 프로세스의 한 지점에서 출발해 고객과 제휴사가 어려움을 느끼는 인접 업무로 확장하는 것입니다. 어디에서 시작했는가보다 중요한 것은 더 넓어진 프로세스를 실제로 운영하고 그 확장을 감당할 수 있는 능력입니다. 기술만으로 수년에 걸친 시스템 연동, 규제준수와 보험금 청구 업무를 유지하기는 어렵습니다. 반복적인 거래, 활용 가능한 데이터, 그리고 크지 않더라도 지속 가능한 수익기반을 가진 플랫폼이 규모를 확대할 때까지 살아남을 가능성이 높습니다.
5. 재보험은 상품설계 단계부터 들어와야 한다
Affinity programme에서 재보험은 상품이 완성된 뒤에만 등장할 필요가 없습니다. 경험통계가 부족한 경우에는 초기 단계부터 참여함으로써 보험회사와 제휴사가 출시 전에 담보범위, 가격, 손해율 변동성과 성장에 필요한 capacity를 함께 검토할 수 있습니다.
개별 programme은 작은 규모로 시작할 수 있지만, 여러 제휴사업을 하나의 포트폴리오로 구성하면 위험분산과 capacity 측면에서 다른 가능성이 생길 수 있습니다. 손해특성에 따라 비례재보험, aggregate protection 또는 기타 맞춤형 구조를 검토할 수 있으며, 이는 신뢰할 만한 데이터와 적용 가능한 위험이전 요건을 전제로 해야 합니다.
6. 차세대 보험 운영기반은 누가 만들 것인가
Affinity Partner는 고객관계를 보유합니다. 모바일 보험대리점은 디지털 판매와 운영을 제공할 수 있습니다. 보험회사는 규제된 위험인수와 상품 capacity를 제공하고, 재보험회사는 위험자본과 글로벌 경험을 더할 수 있습니다. 그러나 이 모든 기능을 하나의 참여자가 단독으로 수행하기는 어렵습니다.
따라서 다음 시장을 만드는 주체는 반드시 하나의 거대한 회사일 필요가 없습니다. 고객접점, 규제된 판매, 기술, 위험인수, 보험금 청구와 재보험을 연결하면서, 보험이 판매된 이후에도 programme 전체가 계속 작동하도록 만들 수 있는 조직 또는 조율된 네트워크가 될 수 있습니다.
미래의 Affinity Insurance는 결제창에 보험 하나를 더 붙이는 사업이 아닙니다. 일상생활 속에 더 나은 protection을 자연스럽게 결합하는 사업입니다. 결국 경쟁을 좌우할 질문은 이를 반복적으로 작동하게 만드는 reusable operating layer를 누가 구축할 것인가입니다.
✈️ Co-Pilot’s Dispatch
대개 시작은 순진한 요청입니다. “우리 고객에게 작은 보험혜택 하나 제공하면 어떨까요?” 간단해 보이지만, 면책사항은 누가 설명하고, 잘못 입력된 고객정보는 누가 수정하며, 파손된 타이어 사진은 누가 검토하고, 보험금은 누가 승인하고, 보험료는 누가 정산하며, 무엇보다 고객이 화가 났을 때 전화는 누가 받을 것인지 묻기 시작하면 이야기가 달라집니다.
회의가 끝날 때까지 모두가 아이디어를 좋아합니다. 다만 실제 운영은 다른 누군가가 해주기를 바랄 뿐입니다. Affinity Insurance에서는 보험증권이 오히려 가장 쉬운 부분일 때가 많습니다.
✈️ Captain’s Salute
Affinity programme이 실패하는 이유는 처음의 아이디어가 매력적이지 않아서가 아닙니다. 판매, 규제준수, 계약관리, 보험금 청구와 위험부담의 책임이 분절되어 있을 때 실패합니다. 이러한 기능을 연결하고 판매 이후까지 책임질 수 있는 조직이 차세대 Embedded Protection 시장을 만들 것입니다.
1. From Affinity to Embedded Protection
Affinity insurance starts with an existing relationship. It may connect a vehicle manufacturer with an owner, a retailer with a customer, a platform with a user, or a pet-care provider with a pet owner. The common feature is not a particular insurance class, but access to a recognisable customer group with a relevant protection need.
Embedded insurance places that protection inside another purchase or service journey. The customer does not begin by visiting an insurer; protection is offered at a relevant point while buying, booking, subscribing or using another service.
Embedded protection broadens the proposition. Customers do not primarily want a policy document. They want a vehicle repaired, a damaged product replaced, a cancelled trip addressed or a veterinary bill managed. Insurance may be one component alongside warranties, assistance, repair networks and other service commitments.
2. Insurance Will Become Less Visible
Insurance is unlikely to disappear. It is more likely to become less visible as it moves into products and services that customers already use.
A vehicle purchase creates exposure to future breakdowns. A newly installed tyre creates exposure to accidental damage. Pet ownership creates exposure to treatment costs. These risks begin where the original retail transaction appears to end—and each can create a new service relationship.
The objective is not to force an insurance offer into every checkout. It is to identify a genuine protection gap in the partner’s customer journey and design cover that operates naturally at the moment of need.
3. Why the Market Has Not Scaled Yet
Korea does not lack affinity ideas. The Korea Insurance Research Institute has identified extended vehicle-quality cover, extended warranties for electronics, return-shipping insurance and motor-related cover among domestic embedded-insurance examples, while highlighting platforms and insurtech capabilities as important drivers of future growth.
The difficulty lies in converting a promising concept into a sustainable programme. An affinity partner wants a simple benefit that customers can understand. The insurer must assess data, pricing, coverage, distribution and consumer-protection requirements. A mobile enrolment screen is only the beginning: policy changes, cancellation, refunds, claims, assessment, repair or replacement, payment and partner reconciliation must all work afterwards.
New affinity risks may lack credible experience data. Low initial volume may not justify the operational cost required from multiple participants. Rapid growth creates a different problem: accumulation, loss-ratio volatility and customer-support demand can expand before pricing and processes mature. A popular proposition and an operationally sustainable insurance programme are not the same thing.
The market is not constrained by a shortage of ideas. It is constrained by the difficulty of converting those ideas into compliant, serviceable and reinsurable programmes.
4. Where the Platform Can Begin
Automotive extended warranty, tyre-damage protection and pet insurance appear to be unrelated products. Operationally, however, they share many components: customer identification, mobile enrolment, policy administration, claims intake, document and image submission, assessment, payment and reconciliation.
This is the case for reusable infrastructure. Instead of building a new system for every product, a common operating layer can support different insured objects, prices, exclusions and claims rules across multiple affinity programmes.
Such a platform rarely appears fully formed. An insurer’s commercial team may move closer to customers, build a service around a particular need and later develop it as a separate business. An insurance agency may begin with enrolment and policy administration, then absorb claims, reconciliation and data functions. An online or offline retailer may extend beyond customer and supplier management into the protection layer itself.
The common pattern is expansion from one point in the process into adjacent activities that customers and partners find difficult. The starting position matters less than the ability to operate the wider process—and to finance that expansion. Technology alone may not sustain years of integration, compliance and claims work. Platforms supported by recurring transactions, usable data and at least a modest but durable revenue base have a better chance of surviving long enough to scale.
5. Reinsurance Should Enter at the Design Stage
In an affinity programme, reinsurance need not arrive only after the product has been completed. Where experience data are limited, early engagement can help the insurer and affinity partner examine coverage, pricing, volatility and growth capacity before launch.
Individual programmes may begin at modest scale, but portfolios across multiple partners can create different diversification and capacity possibilities. Proportional reinsurance, aggregate protection or other bespoke structures may be considered according to the loss profile, subject to credible data and applicable risk-transfer requirements.
6. Who Will Build the Next Insurance Operating Layer?
The affinity partner owns the customer relationship. A mobile insurance agency can provide digital distribution and administration. The insurer provides regulated underwriting and product capacity. The reinsurer can add risk capital and international experience. Few participants can perform every function alone.
The next market-maker may therefore be an organisation—or coordinated network—capable of connecting customer access, regulated distribution, technology, underwriting, claims and reinsurance, while ensuring that the programme continues to work after the policy has been sold.
The future of affinity insurance is not one more policy at checkout. It is better protection embedded in everyday life. The decisive competitive question is who can build the reusable operating layer that makes it work.
✈️ Co-Pilot’s Dispatch
It usually begins with an innocent request: “Could we offer our customers a little insurance benefit?” It sounds simple—until someone asks who explains the exclusions, who corrects the customer data, who reviews the damaged tyre photo, who approves the claim, who reconciles the premium, and, most importantly, who answers the phone when the customer is unhappy.
By the end of the meeting, everyone still loves the idea. They are simply hoping that someone else will operate it. In affinity insurance, the policy is often the easiest part.
✈️ Captain’s Salute
Affinity programmes do not fail because the original idea lacks appeal. They fail when responsibilities across distribution, compliance, administration, claims and risk-bearing remain fragmented. The organisation that can connect those functions—and remain accountable after the sale—will build the next generation of embedded protection.
🇯🇵 日本語 | Summary
Affinity Insuranceは、メーカー、販売店、プラットフォームなどが既に持つ顧客関係から始まります。Embedded Insuranceは、その保障を商品の購入やサービス利用の流れに組み込みます。さらにEmbedded Protectionは、保険だけでなく、Warranty、修理、交換、支払などを顧客の実際の問題解決を中心に統合する考え方です。
韓国市場にアイデアが不足しているわけではありません。課題は、そのアイデアを規制に適合し、継続運営が可能で、再保険も活用できるprogrammeへ転換することです。販売画面だけでなく、契約管理、解約、返金、請求、審査、支払、提携先との精算まで機能しなければなりません。
今後の競争力は、提携先、デジタル代理店、保険会社、再保険会社を結び、複数のprotection商品に再利用できる運営基盤を誰が構築するかによって決まるでしょう。
✈️ Captain’s Salute
Affinity programmeが失敗するのは、最初のアイデアに魅力がないからではありません。Distribution、Compliance、Administration、Claims、Risk-Bearingに関する責任が分断されているときに失敗します。これらの機能をつなぎ、販売後も責任を持ち続けられる組織こそが、次世代のEmbedded Protection市場を構築するでしょう。
🇹🇼 繁體中文 | Summary
Affinity Insurance始於製造商、零售商、平台與既有客戶之間的關係。Embedded Insurance將保障放入商品購買或服務流程,而Embedded Protection則進一步整合保險、保固、維修、替換與理賠,以解決客戶真正面對的問題。
韓國市場並不缺少創意。真正的障礙,是如何把創意轉化為符合監管要求、能持續營運並可獲得再保險支持的programme。除了行動投保之外,契約管理、取消、退款、理賠、審核、支付與合作夥伴結算都必須順利運作。
下一階段的競爭焦點,將是誰能連結合作品牌、數位保險代理、保險公司與再保險公司,並建立可重複支援多種保障方案的營運基礎。
✈️ Captain’s Salute
Affinity programme失敗的原因,並不是最初的構想缺乏吸引力,而是Distribution、Compliance、Administration、Claims與Risk-Bearing等責任彼此割裂。能夠連結這些功能,並在銷售完成後持續承擔營運責任的組織,將建立下一代Embedded Protection市場。
Technical Note: “Embedded protection” may include insurance products, warranties and non-insurance services. Their legal classification, distribution requirements and risk-bearing arrangements differ by structure and jurisdiction. Manufacturer- or seller-provided extended warranty services should not automatically be treated as insurance products.
Sources
- Korea Insurance Research Institute, Embedded Insurance Business Model Cases (2024).
- Korea Insurance Research Institute, Challenges and Opportunities for New Growth (I): Protection Gaps in Korea and New Insurance Business (2023).